Avtaler og pengekrav

Car and engine

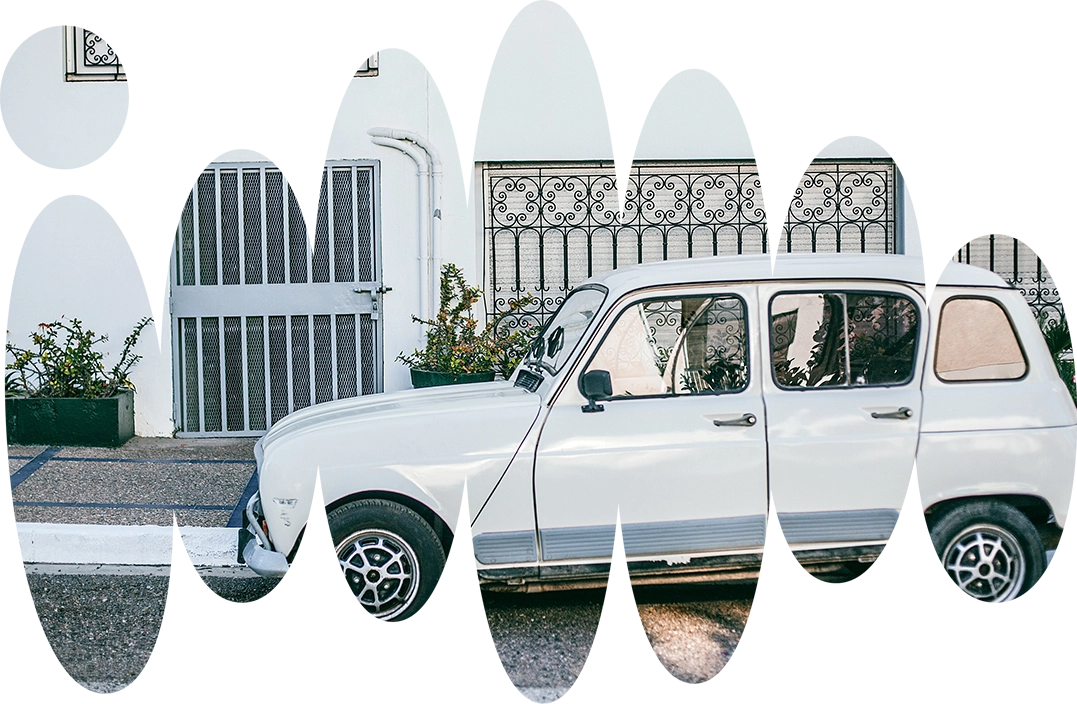
Mangler ved kjøp og salg av bil, båt, MC eller bobil? Vi hjelper deg med reklamasjon, prisavslag og heving – for både kjøper og selger.
Trenger du hjelp fra advokat?

Kjøp og salg av bil, båt, MC og bobil er ofte store avgjørelser, og når det oppdages feil, kan det bli dyrt. Vi hjelper deg som kjøper med å reklamere, kreve prisavslag eller heve kjøpet – og deg som selger med å forsvare deg mot et krav.

For å klage på, eller kreve erstatning for, problemer med en bil må den avvike fra det man normalt kan forvente ut fra alder, bruk og kjørelengde. Det er ikke alltid lett å vurdere selv, så ta kontakt med oss, så finner vi ut av det sammen.

Dekket advokathjelp

Innbo-, bil- og båtforsikringen din har som regel rettshjelpsdekning som dekker store deler av advokatutgiftene, mot en egenandel. Vi sjekker det for deg i første møte. Sjekk dekning her →
How to proceed

1
Gratis kartlegging

15 minutter, ingen forpliktelser. Vi ser på saken din og hva det vil koste.
2
Offers with price guarantee

Du betaler aldri mer enn avtalt. Ingen overraskelser underveis.
3
Du bestemmer

Ønsker du å si ja, signerer du med BankID, så tar vi det derfra.

Book a free meeting

Send us an inquiry

Name
Telephone number
Email
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.

Vi hjelper deg,
uansett hvor i landet

Vi bistår i saker over hele Norge.

Det meste foregår digitalt, så du får kvalifisert juridisk hjelp uavhengig av hvor i landet du bor.

Contact us

Frequently asked questions

Kan jeg heve et bilkjøp?

Ja, hvis bilen har en vesentlig mangel, kan du ha rett til å heve kjøpet. Ellers kan du kreve retting, prisavslag eller erstatning. Hva som gjelder, avhenger av mangelen og om du kjøpte av forhandler eller privatperson.

Hvor lenge har jeg til å reklamere?

Du må reklamere innen rimelig tid etter at du oppdaget – eller burde ha oppdaget – mangelen. Fristene avhenger av hva som er kjøpt og om det er et forbrukerkjøp. Reklamer skriftlig så raskt som mulig.

Hva er forskjellen på kjøp fra forhandler og privatperson?

Kjøper du av en forhandler, gjelder forbrukerkjøpsloven med sterkere rettigheter for deg. Ved kjøp fra privatperson gjelder kjøpsloven, som gir svakere vern. Vi vurderer hvilke regler som gjelder i din sak.

Hva bør jeg gjøre hvis jeg oppdager feil?

Dokumenter feilen med bilder og tilstandsrapport, og send en skriftlig reklamasjon til selger så raskt som mulig. Ikke reparer før du har snakket med oss, siden det kan svekke kravet ditt.

"As is" caveat, what is it?

«Som den er» er et forbehold fra selger som betyr at kjøperen aksepterer en viss grad av risiko for mangler som kan vise seg senere, enten selger har opplyst om det eller ikke. Hvis en kjøper skal fremme krav i et tilfelle hvor en bil er solgt «som den er», må bilen være i vesentlig dårligere stand enn kjøperen hadde grunn til å regne med. Hva kjøper har grunn til å regne med, avhenger blant annet av kjøpesummens størrelse, bruken og øvrige forhold som kan påvirke tilstanden til bilen.

Coverage of legal costs

If you have insurance on your car, you also have legal aid coverage. Your insurance company can then cover the costs of a lawyer from the time the dispute arises - i.e. when it is clear that you and the seller disagree. As a rule, the insurance covers 80% of the legal expenses, but you must pay a deductible of NOK 4,000. We can check for you if you have legal aid coverage in your insurance policy.

Articles

May 5, 2025
Collecting unpaid rent? Here's how to do it
As a landlord, it can be challenging when a tenant fails to pay rent. It is important to act quickly and follow the correct procedures to secure your rights and minimize financial losses.

‍

1. Send a payment reminder

Start by sending a written payment reminder shortly after the due date. This can often remind the tenant of the obligation and lead to prompt payment.

‍

2. Terminate the lease agreement

If payment is still not made, there may be grounds for terminating the lease. According to the Tenancy Act, a material breach is required to terminate, unless otherwise agreed. Not paying rent may constitute such a material breach, especially if it is repeated or occurs over a long period of time. However, in some cases it may be unclear where the line is drawn, and it may be advisable to obtain a legal opinion before taking drastic action.

‍

3. Petition for eviction

If the lease is terminated and the tenant refuses to move out voluntarily, you must file a petition for a variance (eviction) with the bailiff. To do this, you must have a valid basis for enforcement, such as a written lease with an eviction clause for default. You must also have sent the tenant a written notice of eviction before you can file a petition with the bailiff.

‍

4. Use of deposit

If a deposit account has been set up, outstanding rent can be collected from it. This usually requires the consent of the tenant or a decision from the Rent Disputes Committee or the courts. It is important to follow the correct procedure to avoid illegal use of the deposit.

Important considerations

  • Documentation: Keep all correspondence and documentation related to the tenancy and payment follow-up. This is essential in case of any disputes.
  • Professional assistance: Consider seeking help from professional actors such as debt collection agencies or legal advisors to ensure proper handling of the process.
  • Fair Treatment: Although the situation may be frustrating, it is important to treat the tenant fairly and follow the legal requirements throughout the process.

By following these steps, you as a landlord can handle unpaid rent in an efficient and legal manner, while safeguarding your rights. If you would like legal advice, you may want to speak to a lawyer with experience in money claims law .

‍

February 11, 2025
Statute of limitations for monetary claims – Complete guide

Understanding the statute of limitations for monetary claims is essential for both the creditor (claimant) and the debtor (debtor). Statute of limitations means that a claim lapses after a certain period of time, which means that the creditor loses the right to collect the monetary claim. This is regulated in the Statute of Limitations Act.

‍

What is obsolescence?

Statute of limitations means that the right to collect a debt disappears after a certain period of time. This is stipulated by law and exists to ensure that claims cannot be collected many years after they arose.

‍

When a claim becomes statute-barred, it means that the person who owes money no longer has a legal obligation to pay, even if the debt was originally valid.

‍

The general limitation period

The general statute of limitations for monetary claims is 3 years . When the three-year statute of limitations applies, it means that if someone owes you money, you must claim it back within three years, otherwise you lose the right to get it back. As a general principle, the statute of limitations starts to run when the claim becomes due.

Example: If you lend money to a friend on January 1, 2025, and you have not agreed on a specific repayment date, your claim will become statute-barred on January 1, 2028.

‍

Exceptions to the general deadline

Some types of claims have longer deadlines. For example:

  • Claims with a written agreement (debt) which typically include bank loans – If you have a written agreement for the loan, the statute of limitations may be 10 years .
  • Compensation claims – If you claim compensation for an injury, there may be special rules that provide a longer period, up to 20 years in certain cases.

‍

What if you didn't know about the requirement?

In cases where one has not been aware of the requirement, an additional period of one year may be granted from the day one gained or should have gained such knowledge, cf. the Limitation Act, Section 10, No. 1. For contractual obligations, there is an absolute limit of 13 years from the due date, which includes the general period of three years plus a possible extension of ten years.

‍

Interruption of the limitation period

The limitation period can be interrupted in several ways. The most common method is to take legal action against the debtor, for example by filing a settlement complaint or summons. The period can also be interrupted if the debtor acknowledges the claim, either by paying part of the amount owed or otherwise acknowledging the debt.

‍

Absolute limitation periods

For claims for damages outside of a contract, an absolute limitation period of 20 years applies from the date on which the damaging act or the basis for liability ceased, cf. the Limitation Act, Section 9, No. 2. This means that even if the creditor was not aware of the damage or the person responsible, the claim cannot be brought after 20 years. There are exceptions for personal injuries under certain circumstances, where no absolute limitation period applies.

‍

How to avoid the claim becoming time-barred?

If you want to make sure you don't lose your right to your money, you can interrupt the statute of limitations. This can be done in two ways:

  1. Collect the money in an official way
    • Send a payment reminder or dunning letter
    • Hire a debt collection agency
    • Take the case to the conciliation board or court
  2. That the debtor confirms that he or she owes you money
    • Pays part of the claim
    • Written or verbal confirmation that the debt still exists

If the limitation period is interrupted, a new period starts to run from that point.

‍

It is a good idea to know the statute of limitations

Being aware of the statute of limitations is crucial for both creditors and debtors. For the creditor, it ensures that necessary steps are taken to collect claims before they become time-barred. For the debtor, it can mean avoiding paying claims that are no longer valid.

‍

We understand that the rules surrounding statutes of limitations can be complex. If you are unsure about what applies to your situation, it may be a good idea to speak to a lawyer experienced in monetary claims law .

‍

January 16, 2025
Collection of monetary claims as a private individual?
Collecting money as a private individual can be a demanding process, especially if the debtor fails to pay voluntarily. However, as a private individual, you have several options for collecting money claims in a legal and effective manner. This article provides you with a practical guide to how to proceed, from dialogue to enforcement, and what rights you have along the way.

‍

What is a monetary claim?

A monetary claim arises when someone owes you money, either through an agreement, an unpaid invoice or as a result of a loan you have made. The monetary claim can be agreed upon verbally or in writing, but a written agreement makes it easier to prove the claim if disputes arise. Typical situations can be:

  • Loans between friends or family
  • Lease agreements where the tenant fails to pay
  • Unpaid services or sales of goods

‍

Regardless of the background, it is important that the monetary claim is documented. This can be through agreements, messages or receipts, for example.

‍

First step: Communication and negotiation

The first thing you should do is contact the debtor to remind them of the claim. Often, a friendly reminder can be enough to resolve the situation. Here's how you can proceed:

  1. Send a written reminder : This can be an email, SMS or letter requesting that the amount be paid by a specific deadline. Remember to include the amount, due date and any documentation of the claim.
  2. Be factual and professional : Keep your tone professional, even if the situation is frustrating. Good dialogue can prevent unnecessary conflict.
  3. Suggest an installment plan : If the debtor has financial problems, an installment plan can be a good option for both parties.

‍

The debt collection process

If the debtor does not pay despite reminders, you can move on to the next step – collection through debt collection. Here you can choose to handle the process yourself or use a debt collection agency.

  1. Debt collection notice: Before you can start a debt collection case, you must send a written notice of debt collection. This is called a debt collection notice and gives the debtor one last chance to pay before further action is taken. The debt collection notice must contain:
    • A payment deadline of at least 14 days
    • Clear message that the case will be sent to debt collection if payment is not made
  2. Use of a debt collection agency : If the debtor does not pay after the notice, you can contact a debt collection agency. They will handle the process further for a fee.

‍

Enforcement via the bailiff

If debt collection is unsuccessful, you can, as a last resort, request enforcement via the bailiff. This means that the bailiff can seize the debtor's assets or income to cover the monetary claim. To start this process, you must have a so-called basis for enforcement , for example:

  • A verdict from the Conciliation Council
  • A signed debt agreement
  • A payment order

‍

You can send the petition to the bailiff via the police in the debtor's municipality of residence.

‍

How much does it cost to collect a monetary claim?

The costs of collecting a monetary claim will vary depending on the complexity of the case. For example, the use of a collection agency and enforcement will incur fees. In many cases, these costs can be added to the claim, so that it is the debtor who must pay for these expenses.

‍

Prevention of monetary claims

To avoid future conflicts, it is a good idea to ensure good documentation when lending money or entering into agreements. Here are some tips:

  • Create written agreements : A written contract that details the amount, due date, and any interest, provides a strong evidentiary basis.
  • Use Vipps or bank transfer : This gives you a documented payment history that can be used as proof.
  • Avoid oral agreements : Although oral agreements are legally binding, they are often more difficult to prove in a dispute.

‍

Summary

Collecting money claims as a private individual can be a time-consuming process, but by following the right procedure you have a good chance of getting your money back. Always start with dialogue and negotiation, and proceed to debt collection or the bailiff if necessary.

‍

Remember to document your claim thoroughly and act professionally throughout the process. If you need help, you may want to consult a lawyer or debt collection agency for guidance.

‍

Important: It is always important to act quickly when a monetary claim arises, to ensure that it does not become time-barred.

Do you have more questions about how to recover a monetary claim ? Please contact one of our lawyers for individual guidance!

‍

Close

Urgent?

Call us at 21 09 02 02
‍
If it is not urgent, we ask that you book a 15 minute video meeting with us by clicking on this link.

Urgent?
Call us on 21 09 02 02

Book time with us

Book time with us

Voice message via WhatsApp

Book